
Business
Corporate insurance for the inshore and the plant, without the bank script
June 18, 2026 · Jake Brennan
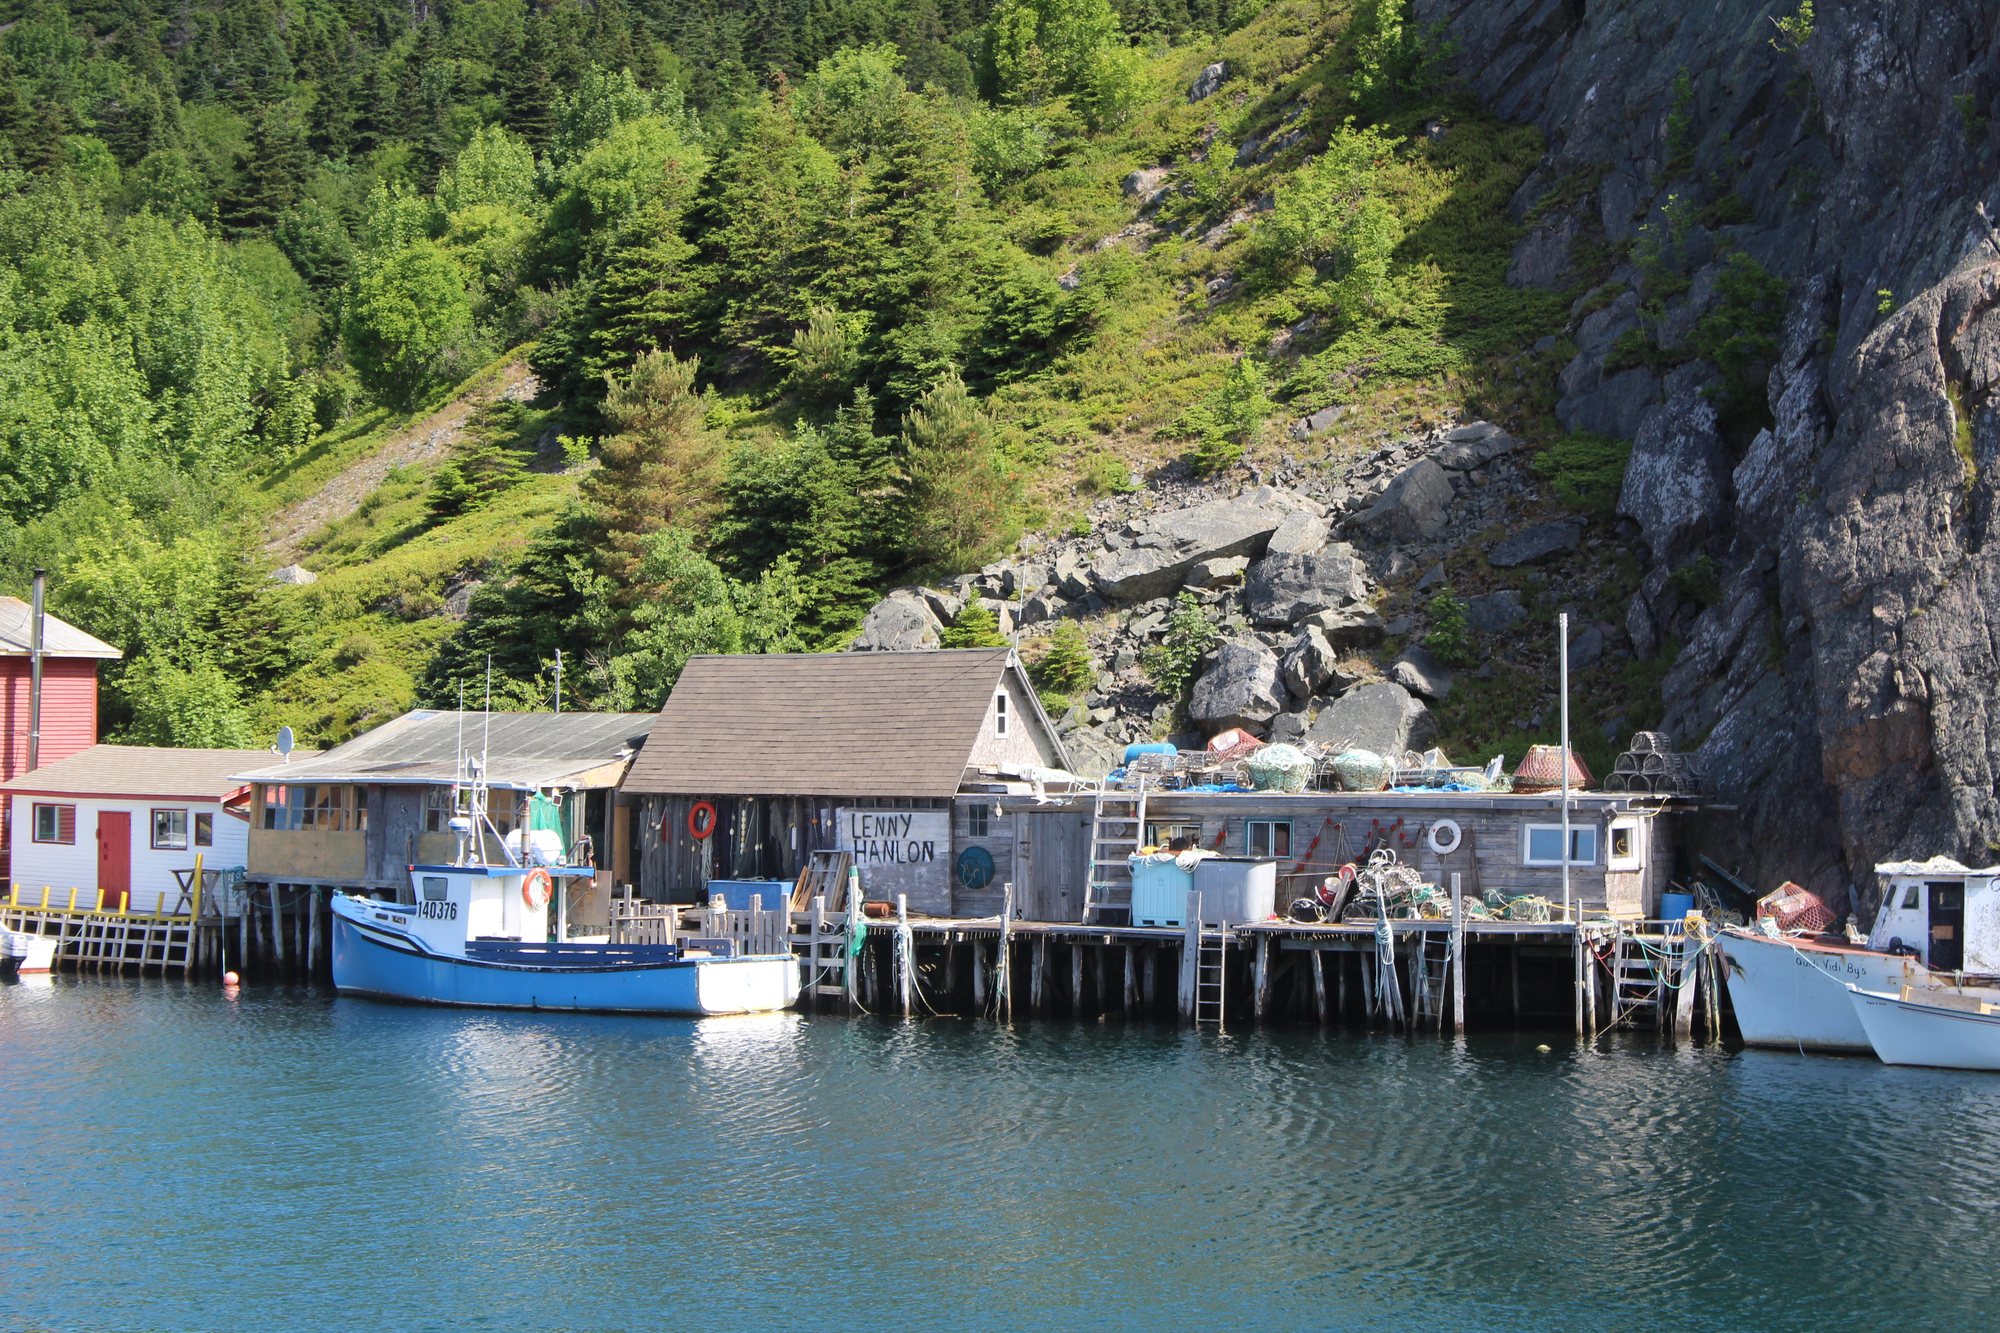
The fishery is not a metaphor on this island. It is still how a great many families eat, employ, and pass something on. When we sit with an owner (a licence holder, a plant operator, a supplier) the first map is people, not products: who cannot be replaced next season, who inherits, and what debt sits against the enterprise.
Key-person coverage is often the missing piece. If the skipper, the plant manager, or the one sibling who runs the books is gone, the bank and the buyers will not wait for grief to settle. A corporately owned life policy can fund a buy-out, keep the lights on, or give the remaining partners time. Term is usually enough at the start. Permanent insurance belongs in the conversation when the company has cash it would rather compound inside a policy than leave sitting, or when the exit is a family transfer rather than a sale.
Group health and dental, even for a crew of eight, is no longer a luxury in a tight labour market. Owners tell us they lose people to a larger outfit over a drug plan. We design benefits that fit a seasonal payroll (not a 2,000-person head-office grid) and pair them with a group RRSP or TFSA when the owner is ready.
Succession in a fishing enterprise is legal, cultural, and financial at the same time. We work alongside your accountant and lawyer. We don’t pretend to replace them. What we do is make sure the insurance and the savings aren’t the last thing anyone thinks about, the week after a diagnosis.